Perpetuals vs Futures in Crypto: Key Differences Explained
Compare crypto perpetuals and dated futures on expiry, holding costs, leverage, liquidation risk, regulation and tax, and see which contract suits your strategy.

Not financial advice.
Key takeaways
- Perpetual futures never expire and use recurring funding payments to stay close to spot, while dated futures settle on a fixed date and converge to spot at expiry.
- Perpetual traders pay or receive a variable funding rate, while dated futures lock the carry cost into the contract price at entry.
- The line between the two is blurring as the CFTC approved the first true US bitcoin perpetual in May 2026, CME moved to 24/7 crypto trading and BitMEX, which invented the crypto perp, closed in September 2026.
On this page 9 sections
- Perpetuals vs Futures at a Glance
- How Dated Crypto Futures Work
- How Perpetual Futures Work
- Funding vs Basis: What Each Contract Costs to Hold
- Leverage, Margin and Liquidation Risk
- Regulation: Where Perpetuals and Futures Are Allowed
- Perp DEXs and Perpetuals Beyond Crypto
- How Perpetuals and Futures Are Taxed
- Bottom Line
Perpetuals vs futures is a choice between a contract that never ends and one that settles on a known date. Both give leveraged long or short exposure to crypto without holding the coin, but they price, cost and behave differently once a trade is open.
Our research team has traded leveraged crypto products on centralised and decentralised exchanges for more than seven years. For this guide we reviewed exchange rulebooks, CFTC filings, funding data and onchain market share.
US traders can now access regulated perpetuals, CME trades crypto futures around the clock and decentralised venues handle a growing share of volume. The old assumption that perpetuals live offshore and futures are regulated no longer holds.
Perpetuals vs Futures at a Glance
A perpetual future is a derivative with no expiry date that tracks spot through funding payments between longs and shorts. A dated future is a contract to buy or sell an asset at a set price on a set date, and its price converges to spot as that date approaches.
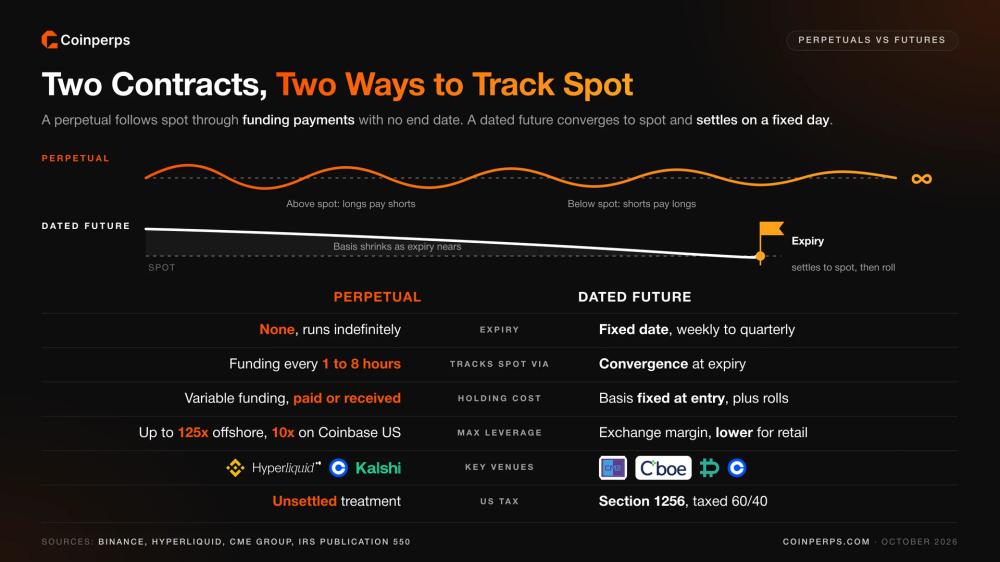
Feature | Perpetual futures | Dated futures |
|---|---|---|
Expiry | None | Fixed date (weekly, monthly or quarterly) |
Price anchor | Funding payments every 1 to 8 hours | Convergence to spot at expiry |
Holding cost | Variable funding, paid or received | Basis locked in at entry, plus roll costs |
Typical maximum leverage | Up to 125x offshore; 10x on Coinbase US | Set by exchange margin; lower for most retail |
Main venues | Binance, Bybit, OKX, Hyperliquid, Coinbase, Kalshi | CME, Cboe, Deribit, Coinbase Derivatives |
Best suited to | Short-term trading and open-ended hedges | Fixed-horizon hedges and basis trades |
US tax treatment | Unsettled | Section 1256 (60/40) on regulated exchanges |
Derivatives made up 77.6% of centralised exchange volume in September 2026, totalling $3.94 trillion for the month, according to CoinDesk Data, and the bulk of that is perpetual swaps. Dated futures still anchor institutional positioning, although Binance overtook CME in bitcoin futures open interest in December 2025, as CoinDesk reported.
Our open interest dashboard tracks live positioning across both contract types.
How Dated Crypto Futures Work
A dated future has a built-in end point, so its price is pulled towards spot as expiry gets closer.
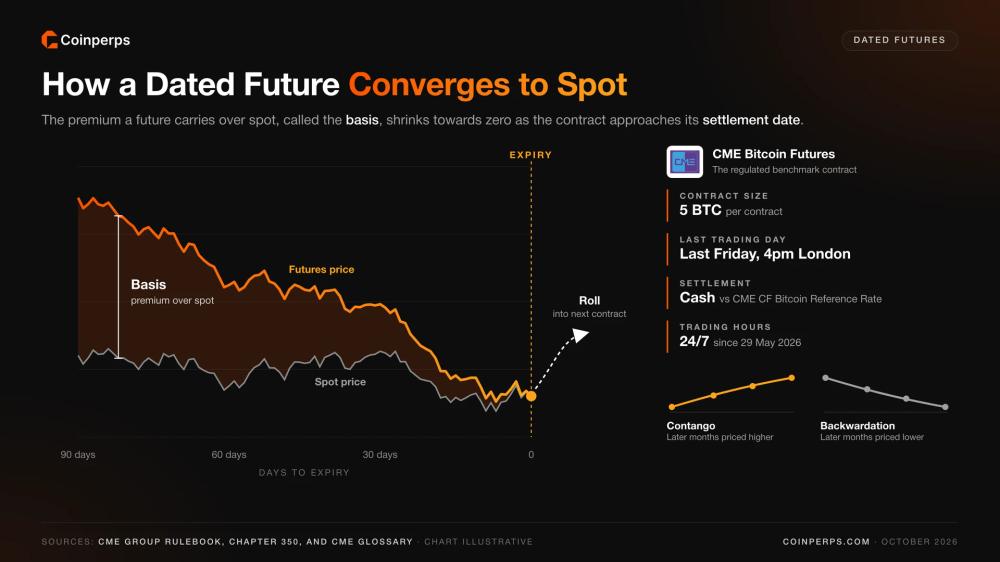
CME's bitcoin futures are the benchmark example. Each contract represents 5 BTC, trading stops at 4pm London time on the last Friday of the contract month, and positions are cash-settled against the CME CF Bitcoin Reference Rate, as set out in the CME rulebook. No bitcoin changes hands, and gains and losses settle in dollars.
Before expiry, a future usually trades at a premium or discount to spot. That gap is called the basis. When later contracts trade above nearer ones, the market is in contango, and when they trade below, it is in backwardation, as defined in the CME glossary. Contango is the normal state in crypto because buyers pay extra for leveraged exposure without tying up cash.
Basis converges towards zero as expiry approaches. A trader who wants to keep exposure beyond expiry must roll, which means closing the expiring contract and opening a later one. CME notes that the price of this roll reflects the cost of carry and can turn negative in severe bear markets.
Regulated venues such as CME and Cboe list dated futures, as do crypto-native exchanges like Deribit and Coinbase Derivatives. Since 29 May 2026, CME's crypto futures and options have traded 24/7 apart from a weekly maintenance window of at least two hours, according to CME Group.
How Perpetual Futures Work
Because a perpetual future never settles, it relies on the funding rate to stop its price drifting away from spot.
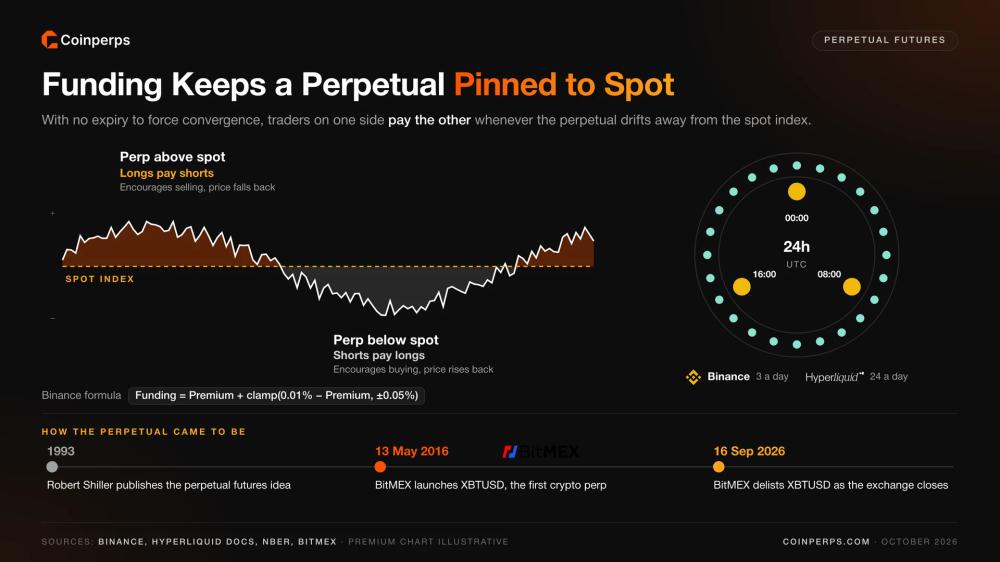
Funding is a periodic payment between traders. When the perpetual trades above the spot index, longs pay shorts, which encourages selling and pulls the price down. When it trades below, shorts pay longs. The exchange does not keep these payments, which pass directly between the two sides of the market.
On Binance, funding is exchanged every eight hours at 00:00, 08:00 and 16:00 UTC. The rate combines a fixed interest component of 0.01% per period with a premium index that measures the gap between the perpetual and spot, as explained in the Binance funding rate guide. Hyperliquid pays funding every hour at one-eighth of the eight-hour rate and caps it at 4% per hour, according to its official documentation.
Exchanges also use a mark price, built from the spot index rather than the last traded price, to value positions and trigger liquidations. This protects traders from liquidation caused by a brief price spike on one venue. Our funding rates tracker shows live rates across major exchanges, and our guide to positive vs negative funding explains what each reading signals.
Economist Robert Shiller proposed a perpetual futures contract decades before crypto, in research later published by the National Bureau of Economic Research. BitMEX turned it into a product in May 2016 with its XBTUSD perpetual swap, offering up to 100x leverage, as announced on the BitMEX blog. A decade later BitMEX delisted XBTUSD and its remaining contracts on 16 September 2026, citing the decision to close the exchange, even as the product it pioneered became the most traded instrument in crypto.
Funding vs Basis: What Each Contract Costs to Hold
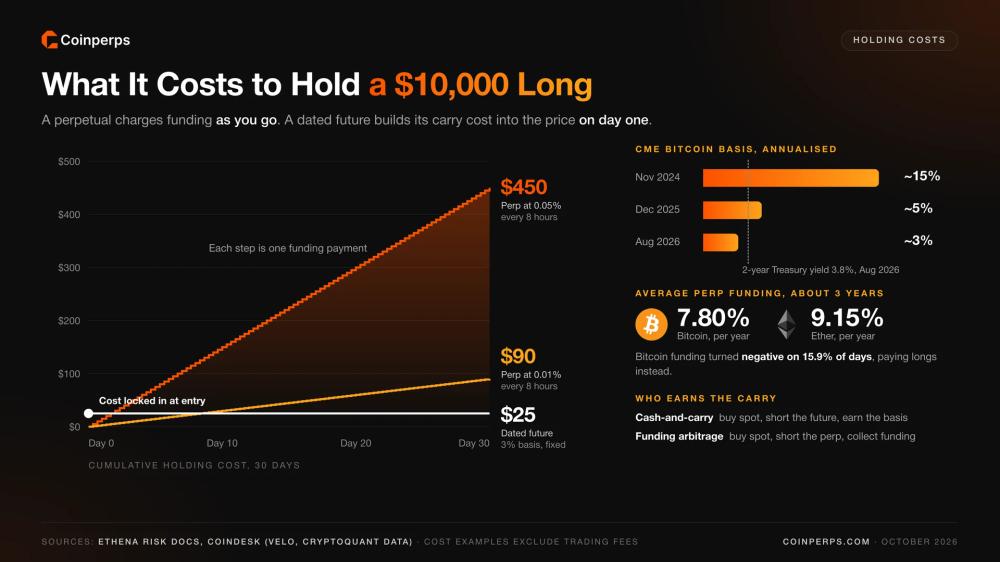
The biggest practical difference between perpetuals and futures is how you pay to hold a position. Perpetual holders pay or receive funding as they go, while dated futures holders pay the carry cost upfront through the basis.
Trading fees are similar for both contract types. Base taker fees on major perpetual venues sit around 0.04% to 0.055%, and maker fees are lower, as our maker vs taker fees guide explains.
At the standard 0.01% funding rate every eight hours, a long perpetual position costs about 0.03% per day, or roughly 11% a year. In heated markets funding can rise several times higher. Over roughly three years, Ethena recorded average annualised funding of 7.80% for bitcoin and 9.15% for ether, with bitcoin funding negative on 15.9% of days, according to Ethena's risk documentation.
A dated future embeds the cost differently. If a quarterly contract trades at a 3% annualised premium, a buyer locks in that cost at entry and it does not change, however hot the market gets. The CME bitcoin basis fell from around 15% annualised after the November 2024 US election to about 5% by December 2025, and to roughly 3% by August 2026, below the two-year Treasury yield, according to CoinDesk.
Holding a $10,000 long for 30 days | Estimated cost |
|---|---|
Perpetual at 0.01% funding per 8 hours | About $90 |
Perpetual at 0.05% funding per 8 hours | About $450 |
Dated future at a 3% annualised basis | About $25, fixed at entry |
The same mechanics create income for the other side. Traders who buy spot and short the future earn the basis in a cash-and-carry trade, and those who buy spot and short the perpetual collect funding, which our guide to funding rate arbitrage covers in detail. Ethena's USDe stablecoin is built on this idea, pairing crypto collateral with short perpetual positions so that price moves in each cancel out, as described in the Ethena documentation.
Leverage, Margin and Liquidation Risk
Higher leverage means a smaller price move can wipe out the margin behind a position, and the limits differ sharply between perpetuals and futures.
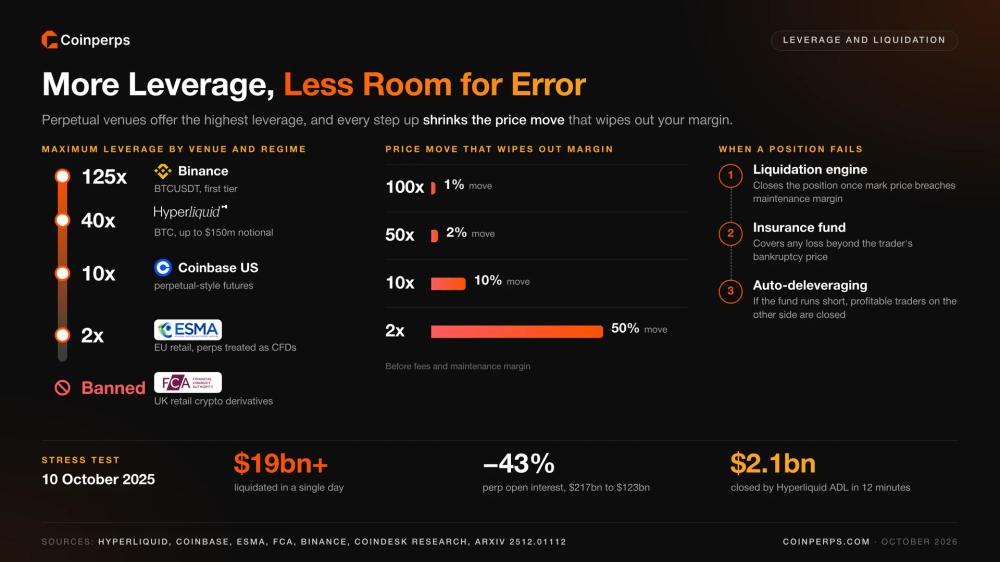
Offshore perpetual exchanges offer the highest limits. Binance allows up to 125x on the first tier of BTCUSDT, falling as position size grows. Hyperliquid caps bitcoin at 40x for positions up to $150 million notional, according to its margin tier documentation. Coinbase's US perpetual-style futures launched in July 2025 with up to 10x leverage, according to Coinbase.
Regulated dated futures work through exchange-set margin. CME sets margin with a risk-based model, so the margin per contract rises when volatility rises. In Europe, ESMA said in February 2026 that products marketed as perpetual futures are likely to fall under national CFD rules, which cap retail crypto leverage at 2:1, according to ESMA. The UK goes further, and the FCA's retail ban on crypto derivatives remains in force.
The distance to liquidation shrinks fast as leverage rises. Before fees and maintenance margin, a 10x position loses its margin on a move of about 10%, a 50x position on about 2% and a 100x position on about 1%.
When a position falls below maintenance margin, the exchange closes it. If it closes beyond the bankruptcy price, the level at which the margin is fully used up, an insurance fund absorbs the loss. If the insurance fund cannot cover it, the exchange uses auto-deleveraging (ADL), closing profitable positions on the other side, as described in the Binance liquidation protocols.
The 10 October 2025 crash showed how this plays out at scale. Perpetual open interest fell 43% in a day, from $217 billion to $123 billion, as more than $19 billion of positions were liquidated, according to CoinDesk Research. Hyperliquid used cross-margin ADL for the first time and closed $2.1 billion of positions in 12 minutes, according to an academic analysis of the event. Our liquidations tracker and guide on how to avoid auto-deleveraging explain how to reduce that exposure.
Regulation: Where Perpetuals and Futures Are Allowed
Regulation decides which contract you can legally trade. Dated futures have been available on US-regulated exchanges since 2017, while perpetuals spent most of their history offshore until regulators opened the door in 2025 and 2026.
United States
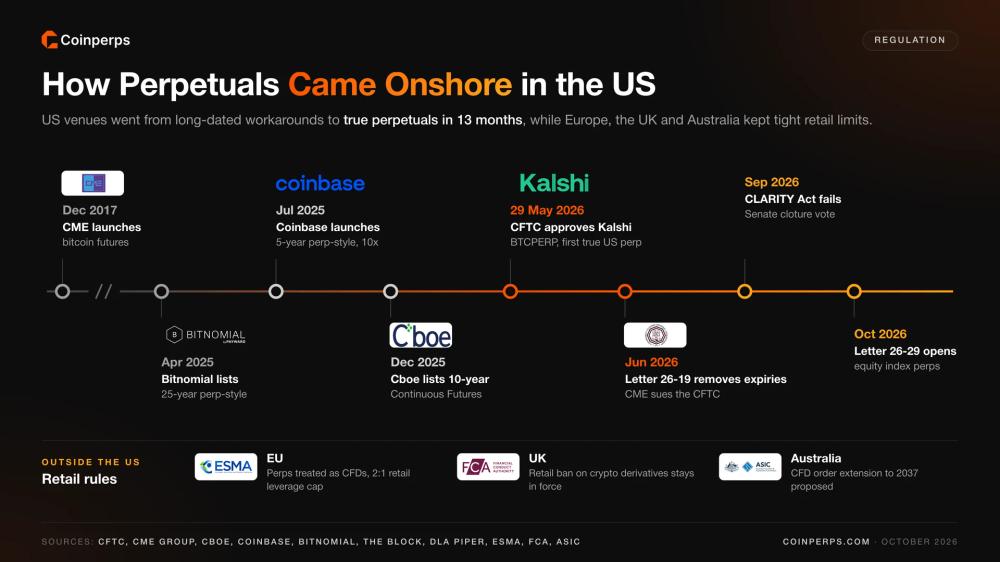
US access to perpetuals arrived in stages. The CFTC requested public comment on perpetual contracts in April 2025. Bitnomial and Coinbase Derivatives then launched "perpetual-style" futures with very long expiries, 25 years for Bitnomial and five years for Coinbase, to fit them within existing futures rules. Cboe followed in December 2025 with Continuous Futures on bitcoin and ether, which carry a 10-year expiry and a daily cash adjustment.
On 29 May 2026 the CFTC approved Kalshi's BTCPERP contract, the first true bitcoin perpetual on a US-regulated exchange. Chairman Michael Selig described it as allowing "a true bitcoin perpetual contract" on a CFTC-registered venue. In June 2026, CFTC Letter 26-19 let Coinbase Derivatives and Bitnomial remove the expiry dates from their perpetual-style contracts, turning them into true perpetuals. Our Kalshi perpetuals review covers the product in detail.
CME sued the CFTC in June 2026, arguing that perpetuals are swaps under the Dodd-Frank Act rather than futures, as reported by The Block. Congress has not filled the gap either, after the CLARITY Act market structure bill failed a Senate cloture vote in September 2026. US policy on perpetuals therefore rests on CFTC orders and staff letters that future leadership could reverse.
Europe, the UK and Australia
Europe treats crypto derivatives under MiFID II rather than MiCA, which covers cryptoassets but not derivatives. ESMA's February 2026 statement means retail perpetuals face the same 2:1 leverage cap, margin close-out and negative balance protection as CFDs. Our guide to the best crypto futures platforms in Europe explains what that means for account choice.
In the UK, the FCA reopened retail access to crypto exchange-traded notes in October 2025 but confirmed that its ban on retail crypto derivatives remains in place. In Australia, ASIC has proposed extending its CFD product intervention order to 2037 and bringing digital-asset-settled CFDs into scope, according to an ASIC consultation opened in October 2026. For a country-by-country view, see our crypto perpetual futures regulation guide.
Perp DEXs and Perpetuals Beyond Crypto
Onchain derivatives exposure is nearly always a perpetual, because dated contracts would split liquidity across many expiries and complicate settlement.
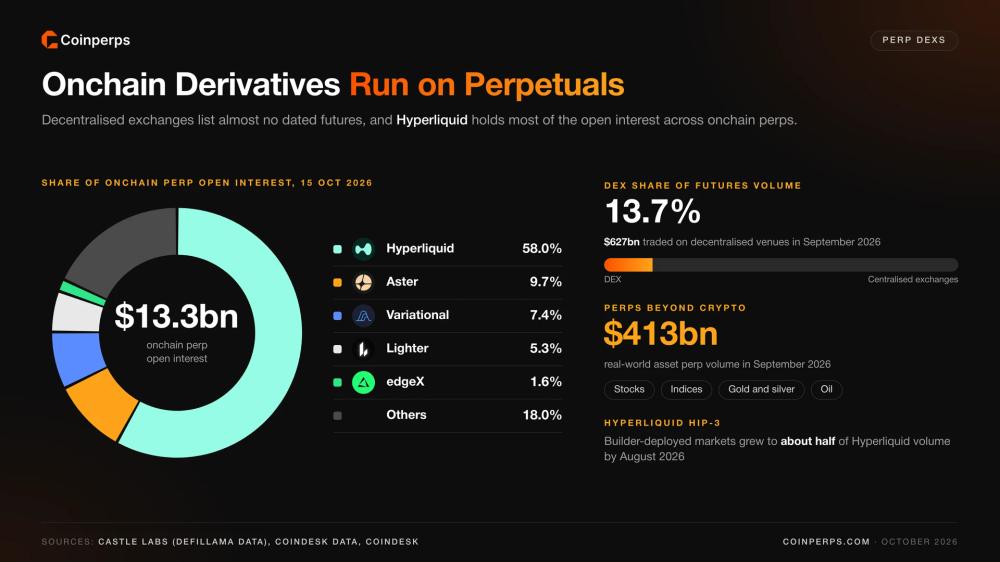
Decentralised venues handled $627 billion of futures volume in September 2026, about 13.7% of the total, according to CoinDesk Data. Hyperliquid holds around 58% of onchain perpetual open interest in mid-October 2026, ahead of Aster, Variational, Lighter and edgeX, according to Castle Labs. Our list of the top decentralised perpetual exchanges and our perp DEX vs CEX comparison cover the trade-offs.
Perpetuals are also spreading beyond crypto. Hyperliquid's HIP-3 upgrade, live since October 2025, lets builders deploy their own perpetual markets by staking 500,000 HYPE, according to the HIP-3 documentation. Markets on stocks, indices and commodities grew to around half of Hyperliquid's volume by August 2026, as reported by CoinDesk.
Across all venues, perpetuals on real-world assets traded $413 billion in September 2026, according to CoinDesk Data. Regulated exchanges are moving the same way, and the CFTC issued Letter 26-29 in October 2026 allowing perpetual-style equity index futures to become true perpetuals. Our guides to HIP-3 perpetuals and the best TradFi perpetual exchanges go deeper.
How Perpetuals and Futures Are Taxed
Your tax position depends on where you live and where the contract trades. Regulated dated futures have clearer rules, while perpetuals often sit in a grey area.
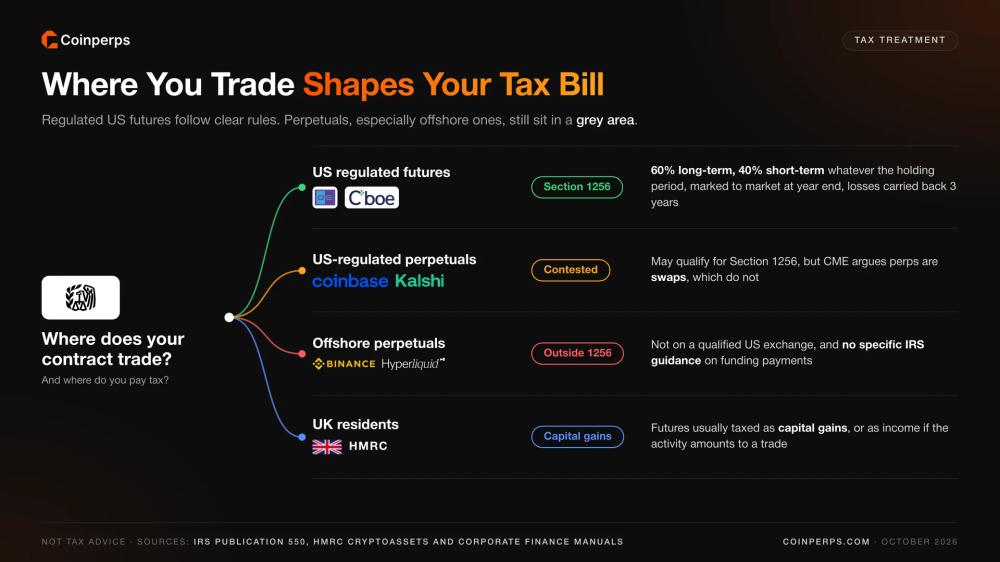
In the US, futures traded on a qualified board or exchange such as CME are Section 1256 contracts. Gains and losses are treated as 60% long-term and 40% short-term regardless of holding period, and open positions are valued at market price at year end, according to IRS Publication 550. Losses can also be carried back three years.
US perpetuals on CFTC-regulated exchanges may qualify for the same treatment, but CME's argument that perpetuals are swaps raises doubts, because swaps do not qualify for Section 1256. Offshore perpetuals traded outside a qualified US exchange fall outside Section 1256, and the IRS has not issued specific guidance on how funding payments are taxed.
In the UK, HMRC says its cryptoasset token guidance does not generally apply to crypto derivatives and points individuals to its rules on financial futures, according to the HMRC Cryptoassets Manual. Profits on futures are usually taxed as capital gains, unless the activity amounts to a trade, in which case they are taxed as income, as set out in HMRC's Corporate Finance Manual. Speak to a qualified tax adviser before filing, because treatment depends on personal circumstances.
Bottom Line
Perpetuals suit traders who want flexible, open-ended exposure and can monitor funding and margin closely. Dated futures suit traders with a fixed time horizon who prefer a known carry cost, regulated clearing and, in the US, clearer tax treatment.
With US exchanges listing true perpetuals and CME trading around the clock, the regulated and offshore worlds now overlap. Compare funding against basis, check leverage limits in your jurisdiction and size positions so a normal day's move cannot liquidate you.


